Gold has a long history as a monetary asset and remains widely held by investors and central banks. That does not mean every investment in gold is safe, profitable or suitable. To assess the advantages of gold, separate the reasons investors hold the metal from the risks of the product used to get exposure.
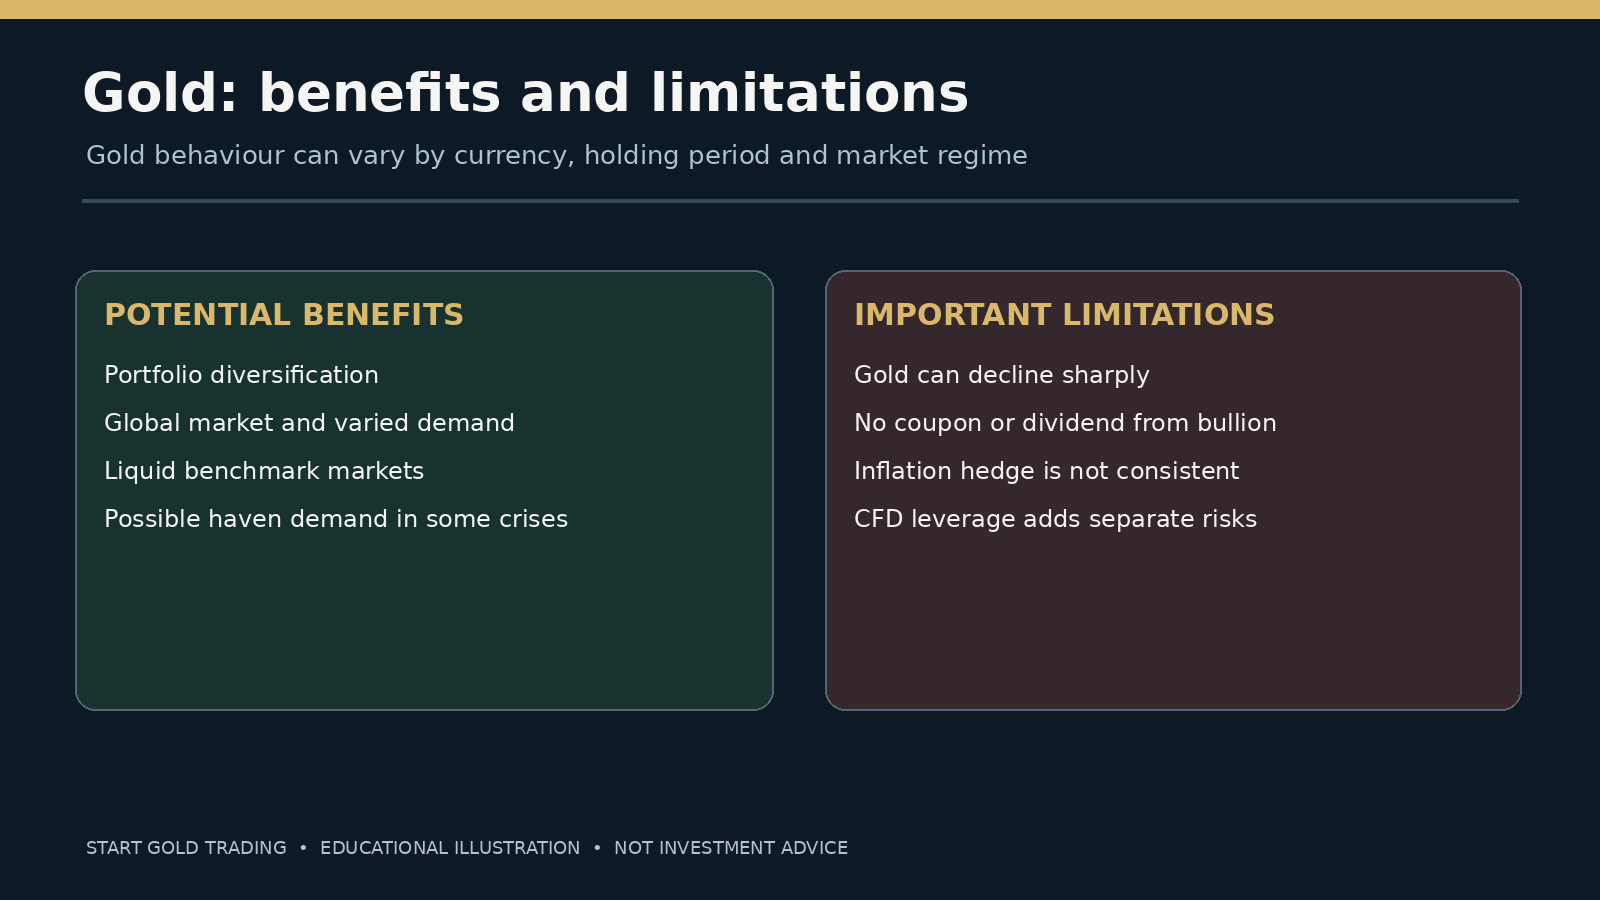
Potential benefit 1: Portfolio diversification
Gold sometimes behaves differently from stocks and bonds, which can make it useful within a wider portfolio. The World Gold Council’s diversification research reviews historical correlations and market-stress periods. However, correlations change, and the existence of a historical diversification benefit does not guarantee protection in the next sell-off.
Potential benefit 2: Global liquidity
Gold is traded internationally across bullion, OTC and exchange markets. Liquid benchmark markets can support frequent transactions, but the liquidity of a particular instrument can still differ. A small physical coin, a fund share and a gold CFD may have different bid/ask spreads, trading windows and counterparty arrangements.
Potential benefit 3: Possible safe-haven demand
Investors have sometimes bought gold during financial stress or geopolitical uncertainty. That is why gold is often described as a safe-haven asset. Yet its price may also decline during crises when investors sell assets to raise cash or when the US dollar and yields change sharply. ‘Safe haven’ is a historical description, not a guarantee of capital protection.
Limitations: Inflation, income and price volatility
- Inflation: gold may help preserve purchasing power over some long periods, but can underperform inflation across shorter windows.
- No contractual yield from bullion: physical gold does not pay interest or dividends; returns depend on resale prices net of costs.
- Price risk: gold can experience material drawdowns even when a long-term holding thesis remains intact.
- Currency exposure: a non-USD investor’s return depends partly on the local exchange rate, not simply the USD gold quote.
- Costs and structure: coins, bars, funds, futures and OTC CFDs have very different custody, financing and liquidation exposures.
A simple product trade-off table
| Exposure | Possible appeal | Important drawback |
|---|---|---|
| Physical gold | Direct ownership of a tangible asset | Storage, premiums and resale spreads |
| Gold-linked funds | Convenient market access | Ongoing fees and tracking or fund-structure risk |
| Gold futures | Standardised exchange trading | Expiry, margin and possible forced close-outs |
| Gold CFDs | Directional exposure without bullion delivery | Leverage, financing, spreads and provider risk |
In particular, a gold CFD does not create a defensive portfolio holding just because the reference asset is gold. For example, a trader exposed to $20,000 worth of gold through a leveraged CFD faces a $200 price loss before costs from a 1% adverse change in the quoted notional value. If they posted only $1,000 in margin, that loss is 20% of initial margin, even though the metal moved only 1%. This is a hypothetical proportional illustration; actual contract specifications vary.
Gold and modern currencies
Gold once formed part of major monetary systems, but most modern currencies are fiat currencies, not directly exchangeable for a fixed quantity of gold. Central banks may hold gold as a reserve asset without the currency being formally backed or redeemable in gold. Avoid equating reserve holdings with a gold standard.
How to evaluate a gold investment thesis
- Define the purpose: long-term diversification, shorter-term trading or another objective.
- Choose the actual product and check ownership rights, issuer/provider risk and fees.
- Review performance in multiple market environments rather than selecting only crisis periods.
- Consider whether a gold allocation would add genuine diversification to existing holdings.
- Decide what adverse outcome would invalidate the thesis and whether the potential loss is affordable.
Key takeaway
Gold has characteristics that may make it useful, but diversification and inflation protection vary by period. The instrument matters: physically owned bullion and a leveraged CFD have fundamentally different risks. See the World Gold Council’s strategic-asset research and MoneySense’s explanation of CFDs.
Sources
- World Gold Council — Gold as a Strategic Asset
- World Gold Council — Diversification
- MoneySense — Understanding CFDs
Continue learning
- Gold Trading for Beginners — Five-Stage Learning Guide
- Gold CFDs Explained: How XAU/USD Trading Works
- How to Choose a Gold CFD Broker
Educational information only. Gold prices and leveraged derivatives can produce substantial losses. Examples are hypothetical and are not personal financial advice.