Trading and investing describe how long an exposure may be held and why it is held, not a guaranteed ranking of profitability. A trader may speculate over minutes or days while an investor may hold bullion or fund shares for years. The instrument’s ownership rights, costs and risks can matter more than the holding period.
At a glance · Estimated reading time: 4–5 minutes
- Ownership of bullion or fund units differs from an OTC CFD or a futures position.
- Holding two gold-linked products can increase concentration instead of diversification.
- Measure losses against the entire exposure, not only the margin deposit.
What does the investor or trader actually hold?
| Exposure | Legal or economic interest | Typical considerations |
|---|---|---|
| Physical bullion | Ownership of bars or coins | Premium, custody, security and resale spread |
| Gold-backed fund or ETF | Shares or fund units, not direct personal possession of bars | Fees, tracking and fund structure |
| Gold futures | Exchange-traded contract | Margin, expiry, roll and settlement rules |
| Gold CFDs | OTC contract with a dealer | Leverage, funding, liquidation and counterparty risks |
| Gold-mining shares | Equity interest in a business | Company risk beyond bullion price |
Why longer-term gold is not automatically safe
Gold does not pay interest or dividends simply because the metal is owned. It can also suffer deep drawdowns and underperform inflation in particular periods. The World Gold Council’s 2026 assessment discusses substantial historical price declines as well as gold’s long-term role. ‘Safe haven’ is not a contractual promise of capital preservation.
Why trading with low margin can be particularly risky
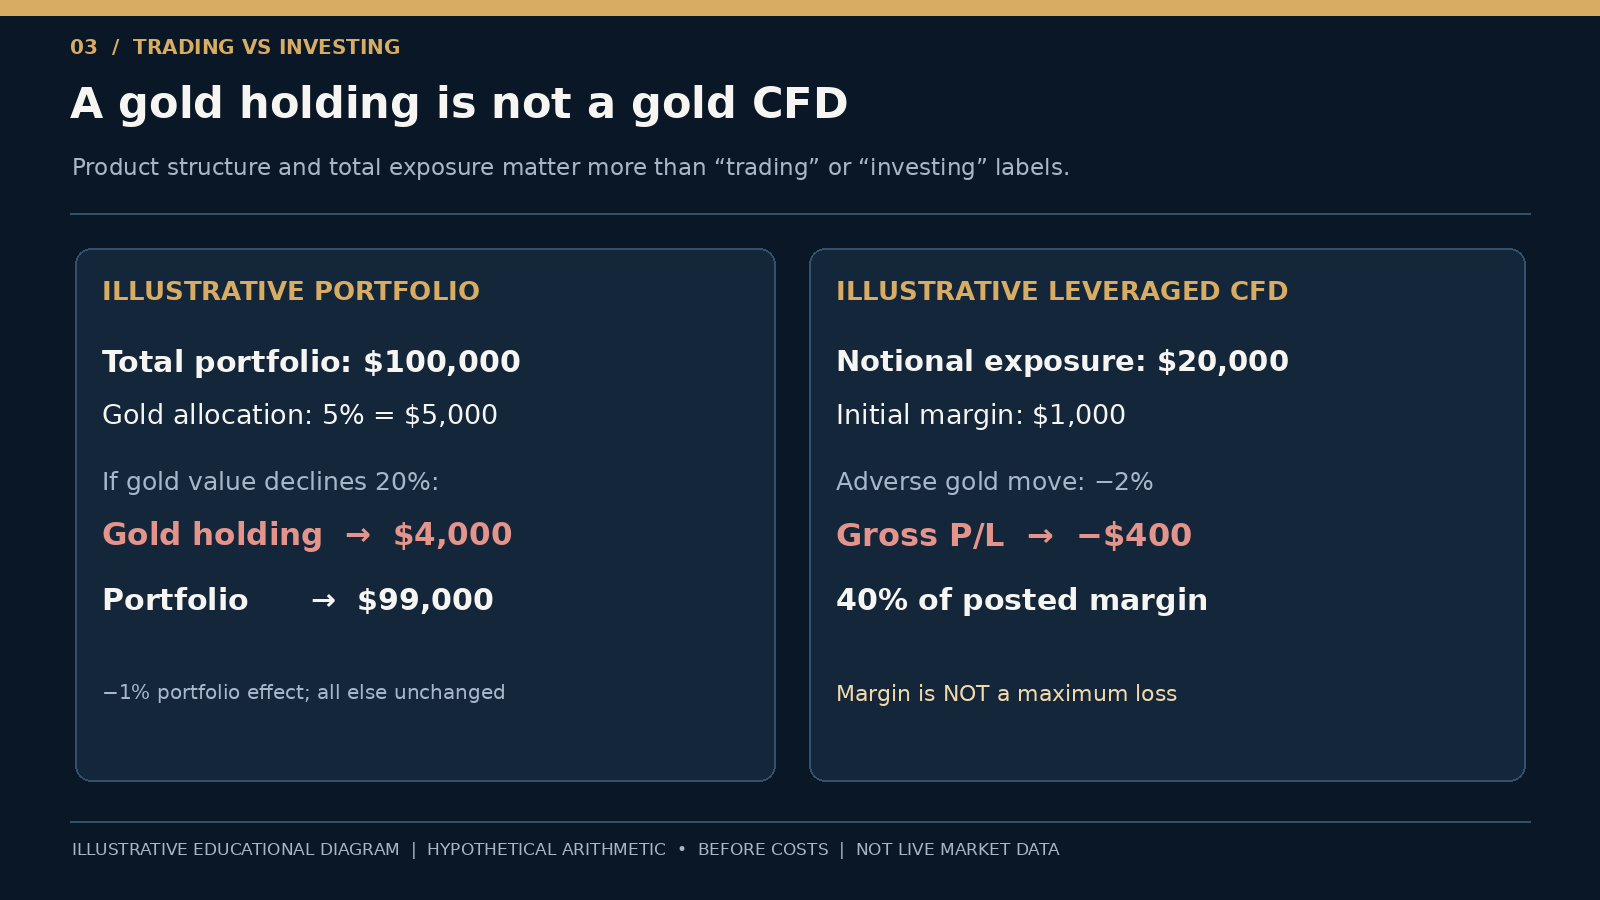
Suppose a hypothetical CFD represents $20,000 of gold exposure and requires a $1,000 initial deposit. A 2% move against that exposure produces a $400 gross loss before costs: 40% of the deposited margin, even though gold moved only 2%. Further moves, margin changes or poor execution can create larger losses. Deposited margin is not an insurance fund.
Long-term allocation: a hypothetical scenario
Consider an illustrative $100,000 portfolio with 5% allocated to physically owned gold or a fund holding. That gold component starts at $5,000. If its value declines 20% while every other holding is unchanged, the gold portion falls to $4,000 and the total portfolio becomes $99,000 before fees—a 1% portfolio decline from this movement alone. This is not a recommendation to invest 5% or a forecast.
Comparing costs over time
- Physical metal may require dealer premiums, safekeeping, insurance and a resale spread.
- Gold-linked fund shares can incur ongoing expenses and tracking differences.
- Futures positions have contract expiration, commissions and margin changes.
- CFDs may accrue overnight financing and can be closed by the provider if margin is insufficient.
- An investor using a different base currency also faces exchange-rate effects.
Could someone hold investments and also trade?
It is possible to hold an investment while taking speculative positions, but the combined exposure must be measured. A physical gold holding plus a leveraged long gold CFD can increase concentration instead of providing diversification. The risks may be highly correlated even though the account labels differ.
Questions to ask before choosing
- Is the purpose diversification, physical ownership, a short-term price view or another goal?
- Which legal asset, security or contract will I actually hold?
- What is the worst plausible loss, including charges and adverse fills?
- Can I afford to hold through a large drawdown without needing the money for essentials?
- Are counterparty and currency exposures already present elsewhere?
- Would remaining uninvested or learning without a live position be more appropriate?
Practice: identify combined gold exposure across two accounts
Suppose a fictional $100,000 portfolio holds $5,000 of unleveraged gold exposure and also has a $20,000 notional long gold CFD requiring $1,000 of margin. Assume both respond one-for-one to the same hypothetical percentage change in gold for this exercise. This is not a recommendation to hold either position.
Reveal 1 — What happens to the unleveraged gold holding if the gold price falls 2%?
2% × $5,000 = $100 decline in the gold holding, before any product costs or tracking differences.
Reveal 2 — What is the CFD’s gross effect of that same 2% adverse move?
2% × $20,000 notional exposure = $400 gross loss. It is not capped at 2% of the $1,000 margin. Depending on the account and contract, a leveraged position could lose more than deposited margin.
Reveal 3 — What is the combined illustrative loss, and why might the label ‘diversified’ mislead?
$100 holding decline plus $400 CFD gross loss = $500 combined loss before spread, financing, FX and other charges. The products use different legal wrappers, but both were exposed to the same fall in gold. Account holdings and actual sensitivities must be assessed together.
The aim is to compare economic exposure and legal ownership. A fund share may track a gold benchmark imperfectly, and a CFD has its own contractual and counterparty risks. Before buying another gold-linked product, write down the exposure it adds and whether it offsets or compounds existing risks.
Key takeaway
Gold trading and gold investing can both lose money. Compare product structure, exposure and costs rather than assuming trading always grows wealth faster or investing always preserves it.
Continue learning
References
- World Gold Council — Risks and Challenges of Gold
- MoneySense — Understanding Contracts for Difference
- CME — Gold Futures Specifications
Educational information only. All numerical examples are hypothetical, not historical or current quotes. Neither trading strategies nor stop orders guarantee profit or a fixed loss ceiling. Leveraged products can cause substantial losses.