Discipline in gold trading is about managing exposure and execution rather than memorising motivational rules. A stop-loss is an instruction subject to a provider’s terms, not an insurance policy against unexpected losses.
Start with product specifications
An XAU/USD CFD may be quoted per troy ounce of gold, but the provider determines its actual unit/lot size, minimum increment, spread, overnight charges and stop execution. A trading plan is incomplete until the relevant contract specification is known. Initial margin is collateral, not a loss cap.
Hypothetical 1% planned-risk example
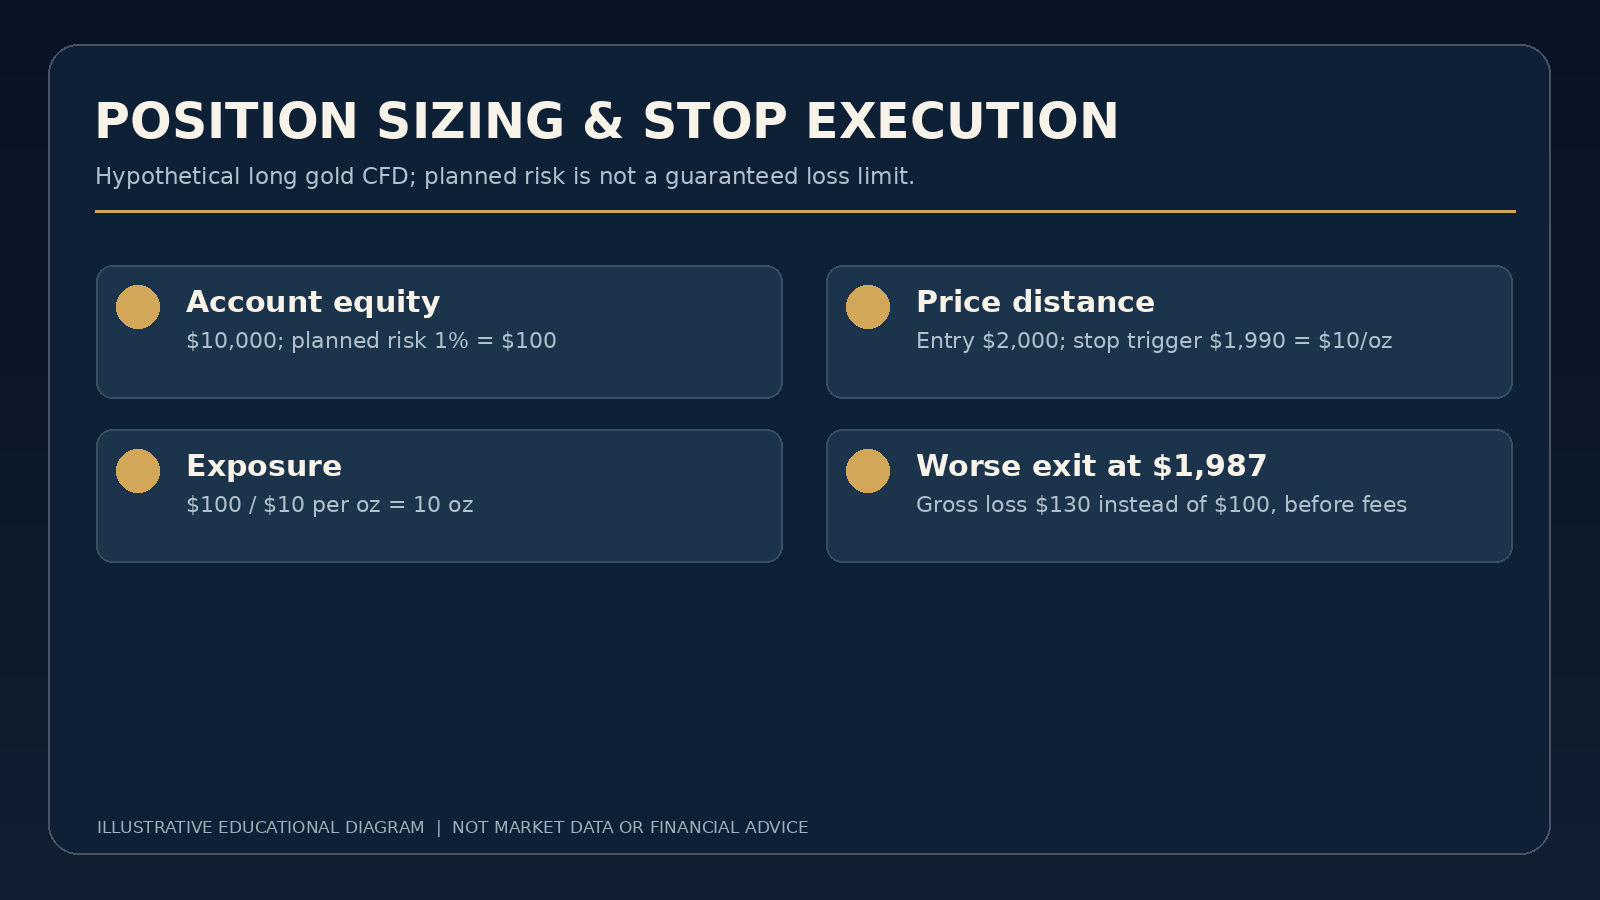
Suppose account equity is $10,000 and a trader independently chooses a 1% planned risk budget, or $100. A hypothetical long position enters at $2,000 per ounce and sets a stop trigger at $1,990, which is $10 below entry. Position exposure of $100 divided by $10/oz equals 10 ounces before costs, if the provider supports that quantity.
| Calculation | Hypothetical value |
|---|---|
| Planned risk | 1% × $10,000 = $100 |
| Entry to stop | $2,000 − $1,990 = $10/oz |
| Ounces of exposure | $100 / $10 = 10 oz |
| Stop filled at $1,987 | 10 × $13 = $130 loss, before costs |
This example shows why a chosen 1% budget is not a guaranteed maximum loss. Gaps, bid/ask changes, missed executions, financing and additional open positions can make realised losses larger. MoneySense notes non-guaranteed CFD stop measures.
Six practical boundaries
- Define the market observation that permits an entry and the event that invalidates it.
- Calculate exposure from the stop distance and a planned amount of risk, then check the broker’s minimum lot size.
- Review the calendar for major data releases and the provider’s session or holiday breaks.
- Avoid opening several correlated positions while evaluating each trade as independent.
- Set a session pause rule for repeated deviations or an unacceptable loss, but recognise real fills can exceed the intended boundary.
- Reconcile actual fills, commissions and positions with the trading journal.
Discipline is not the same as never changing an order
A planned stop should not be widened reflexively to avoid accepting a loss. But it is also necessary to understand bid/ask triggers, whether an order was actually accepted and the possibility of a forced margin close-out. Correct behaviour depends on the specified order and the account’s risks, not slogans.
A no-trade decision can be valid
If the minimum CFD size is too large for the budget, the spread becomes abnormal or the relevant data feed is unreliable, remaining flat is an actionable form of discipline. There is no obligation to open a position each day.
Key takeaway
A good risk routine clarifies quantity, price distance and execution failure scenarios. It does not ensure that a strategy has an edge or a broker will honour a requested exit price.
Continue learning
Sources
Educational information only; none of the hypothetical examples constitute current market quotes, verified return expectations or financial advice. Leveraged trading carries substantial risks.