A gold trading platform advertising low spreads or zero commission is not necessarily the cheapest place to hold the same exposure. Fees depend on the legal product, provider, account type, transaction size, trading session and holding period. This guide explains how to calculate comparable gold trading costs, using fictional broker quotes rather than presenting an unverifiable 2026 leaderboard.
1. Start with the legal product and unit of exposure
Before comparing two gold quotes, establish whether both represent the same OTC CFD, gold future, fund unit or bullion trade. CME Gold futures have standardised contract units—GC is 100 troy ounces, MGC is 10 ounces and 1OZ is one ounce—but retail XAU/USD lot sizes depend on individual providers. Comparing ‘0.01 lots’ without converting to ounces can create false conclusions about affordability.
2. Read the spread in dollars per troy ounce
The bid is a price at which a market buyer is prepared to buy; the ask is the price offered to a buyer of the asset. A trader opening a long CFD may pay the ask and closing it may receive the bid. For a completely fictional bid of $2,000.00 and ask of $2,000.80, the spread is $0.80 per ounce. On five ounces, an immediate buy-and-sell at unchanged quotes creates a $4 gross spread difference. Broker ‘pips’ or points may use different decimal conventions; convert into actual dollars per ounce first.
3. Add commissions on both sides
A raw-spread account might advertise a narrower quote but charge an opening and closing commission. Compare the total charge for the same five-ounce quantity, not just the advertised spread. Some providers report commission per lot, per side, or for a full round trip. Each convention must be converted to the same dollar basis before selecting a hypothetical cheaper structure.
4. Worked example: two fictional pricing plans
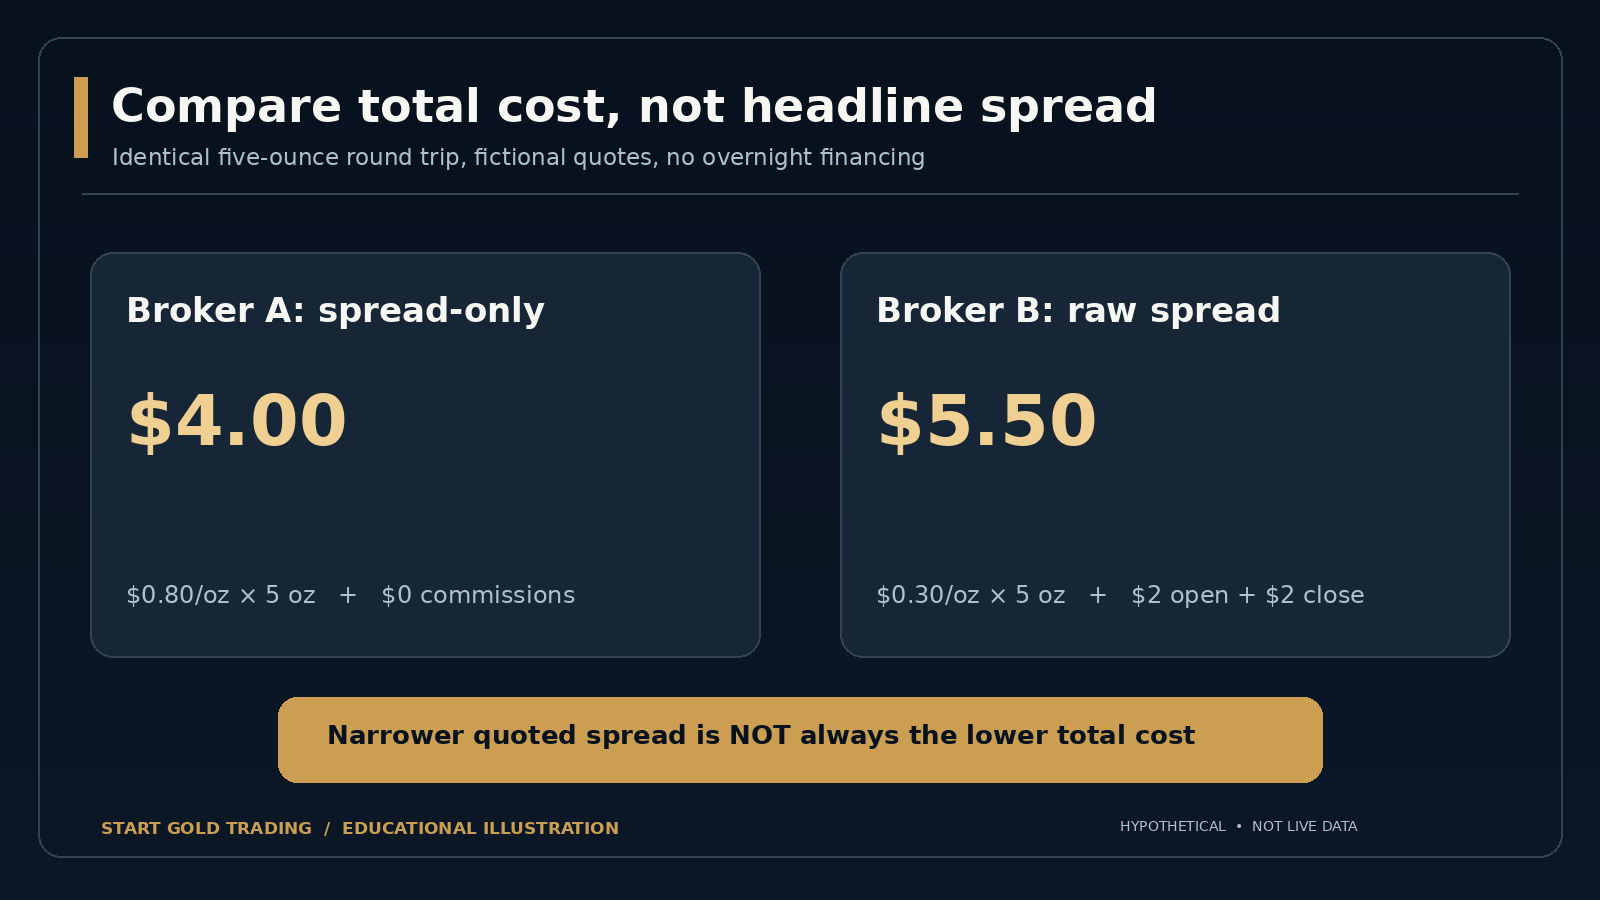
Both fictional brokers below provide the same five-ounce exposure, identical fills and no overnight position. Broker A quotes a $0.80/oz spread and no separate commission; Broker B quotes a $0.30/oz spread and charges $2 when opening plus $2 when closing. Broker A costs $4; Broker B costs $5.50 on the stated round trip, before any other charges. The narrower headline spread did not create the lower all-in expense.
| Hypothetical fee | Broker A | Broker B |
|---|---|---|
| Bid/ask spread | $0.80/oz | $0.30/oz |
| Spread × five ounces | $4.00 | $1.50 |
| Opening commission | $0.00 | $2.00 |
| Closing commission | $0.00 | $2.00 |
| Total round trip | $4.00 | $5.50 |
5. Include financing for overnight holdings
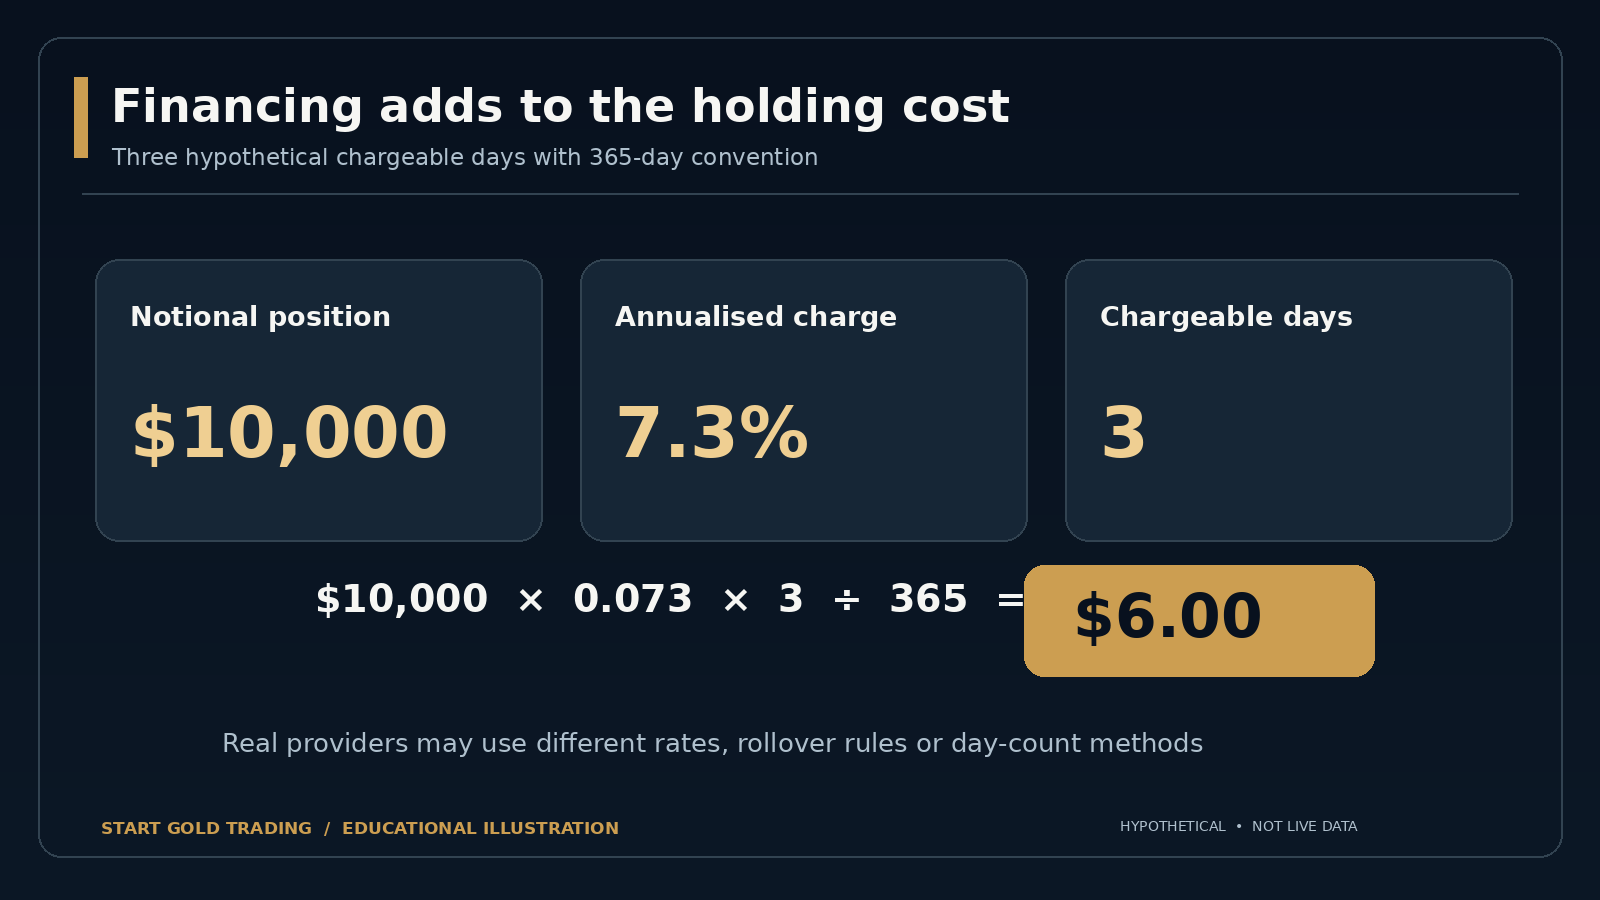
CFDs may charge financing based on notional position value and day-count conventions. As a separate hypothetical illustration, suppose $10,000 of notional exposure incurs a 7.3% annualised financing charge and is held for three chargeable days using a 365-day year. Financing would be $10,000 × 0.073 × 3 / 365 = $6.00. Providers may use different rates, benchmarks, debit/credit terms, rollover times and multipliers, including special weekend adjustments. Ask for an actual fee statement before assuming this model applies.
6. Slippage can outweigh a quoted commission saving
A market instruction is not a guarantee of the price visible when it was sent. During an economic release, quotations may move rapidly, spreads may widen or the order may not execute as requested. A stop trigger can close at a worse price; a stop-limit may remain unfilled. A $0.20/oz additional adverse exit on a five-ounce hypothetical CFD changes gross result by $1, even before extra time in the market or other costs. See MoneySense’s CFD guidance for stop, margin and counterparty limits.
7. Compare currency conversion and account charges
If an account reports in SGD while gold is quoted in USD, conversion fees or currency movements can change the net SGD result. Other possible charges include data fees, platform subscription, deposit/withdrawal fees and inactivity conditions. Fund units have ongoing expenses, while bullion may have storage and resale costs. Compare the exact product’s full cost of ownership instead of treating all gold instruments as interchangeable.
8. A low deposit is not a low-cost safety test
Leverage reduces required collateral but not the dollar effect of adverse gold moves. Suppose a provider requires $1,000 margin for $10,000 of notional exposure; a 2% adverse change yields a $200 gross price loss, before fees. A tiny deposit threshold can coexist with a much larger maximum financial loss. Singapore MoneySense treats CFDs as Specified Investment Products requiring the applicable Customer Knowledge Assessment.
9. Validate providers and document the quote snapshot
A cheap quote is useful only if a genuine firm will honour the contract under transparent terms. Singapore consumers should verify legal names and activities in the MAS Financial Institutions Directory and use official contact details rather than referral messages. Retain the instrument name, exact quote timestamp, account type, lot-to-ounce conversion, commission table, financing method and contract-version date. Today’s quote should not be inserted into an evergreen article as a permanent advertised rate.
A complete cost-comparison worksheet
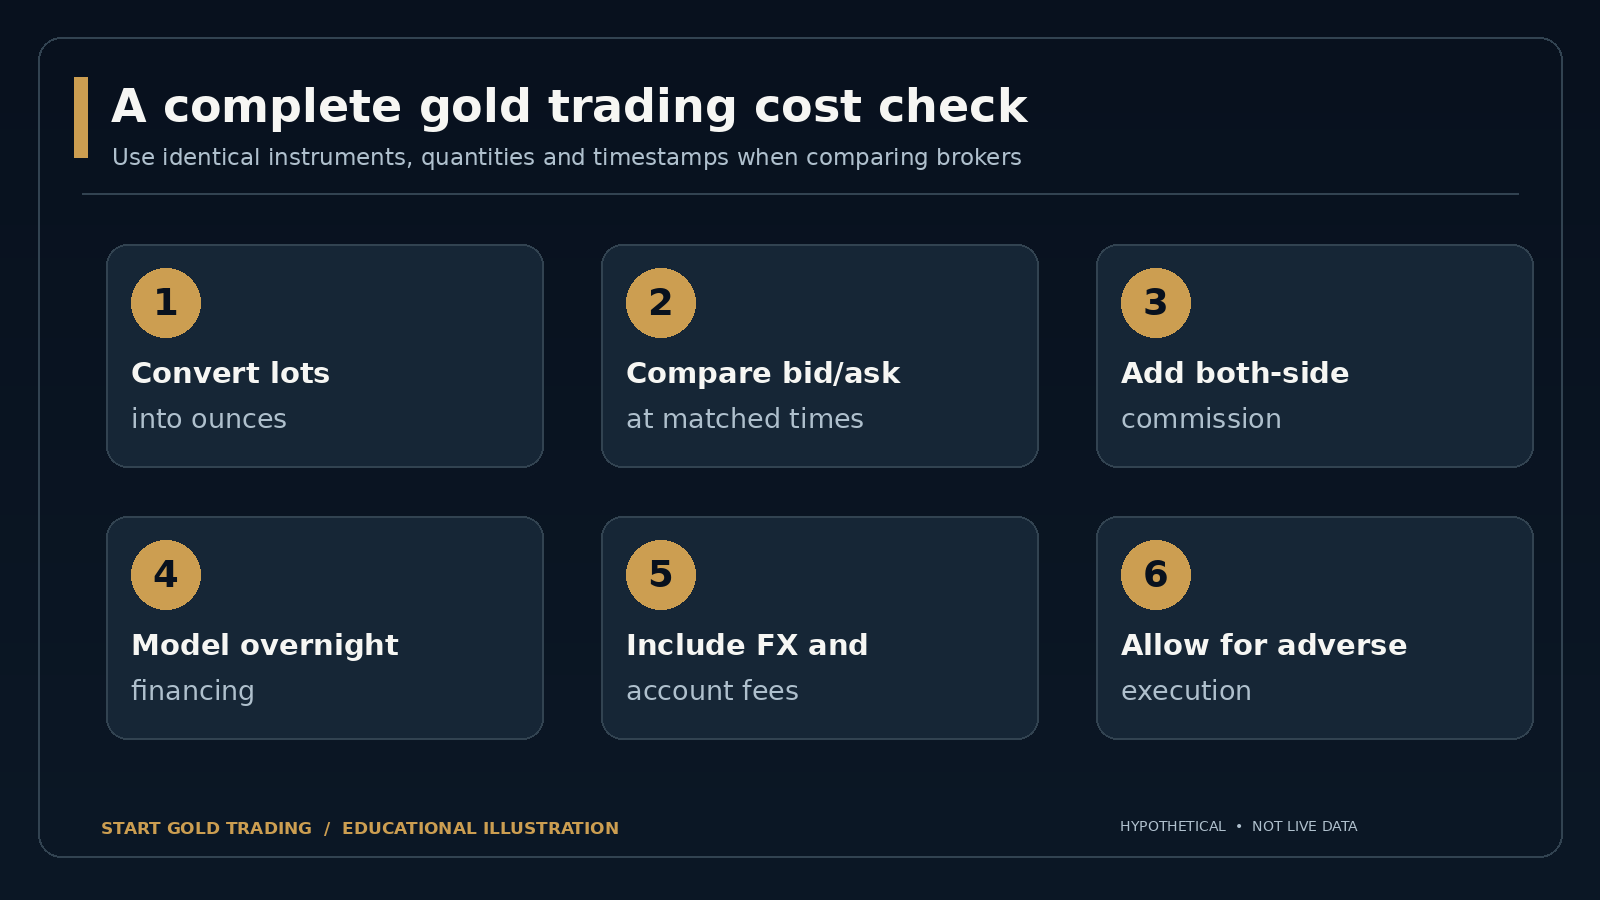
- Identify the provider and the legal gold instrument.
- Convert both positions to the same underlying ounces.
- Record bid and ask at closely matched times; calculate dollar spread.
- Add each entry and exit commission, on the correct unit basis.
- Model financing for the expected number of chargeable days.
- Include conversion, data and account fees that actually apply.
- Compare possible adverse fills and provider dealing conditions.
- If the minimum contract creates excessive losses or terms cannot be verified, remain flat.
Frequently asked questions
- Is zero commission free trading? No; spread, financing and other costs can remain.
- Is the smallest displayed spread always cheapest? No. Round-trip costs and execution matter.
- Are quoted spreads fixed? Usually not; consult current instrument terms.
- Do low spreads guarantee profits? No. Prices and position exposure still determine outcomes.
- Which platform is currently cheapest? A defensible answer requires contemporaneous, like-for-like quotes and legal-entity checks.
Key takeaway
The fairest gold trading platform comparison is an itemised, dated calculation of the full cost of the same exposure. A ranking without consistent contract units, realistic financing and execution assumptions is not reliable.
Related gold education
- Gold Trading Resources
- Choosing a Gold Trading Platform
- Beginner Gold Trading Guide
- Original related resource
Official references
- MoneySense — Understanding Contracts for Difference
- MAS — Financial Institutions Directory
- CME — Gold Futures Product Specifications
- Investor.gov — Stop Orders and Execution
Education only. Company comparison labels and all dollar amounts in worked examples are fictional; not current broker quotes, guaranteed returns or personal financial advice. Gold derivatives carry substantial loss risk.